

Denver stopped being the “affordable mountain city” a while ago. If you moved here for the outdoor access and cheaper rent than Boulder, you’ve probably noticed both of those selling points have quietly eroded — the rent part especially.
A lot of that is remote workers and out-of-state transplants who could afford San Francisco or Austin prices bidding up neighborhoods that used to be starter-apartment territory. Cash stuffing Denver Colorado locals are turning to isn’t a random trend — it’s a reaction to a city where six years of population growth reset what “normal” rent and “normal” going-out spending look like.
Between RiNo’s brewery crawl, LoHi’s restaurant rows, and a housing market that’s pushed a lot of people out toward Aurora, Lakewood, and Littleton chasing lower rent, this city makes it easy to spend without noticing. Cash stuffing works because it puts a hard stop where a tap-to-pay card doesn’t.
Here’s how it actually works if you live here — accounting for Denver prices, Denver habits, and a cash culture this city has for reasons most budgeting advice never mentions.
What Cash Stuffing Actually Is (And Why Denver Makes It Harder)
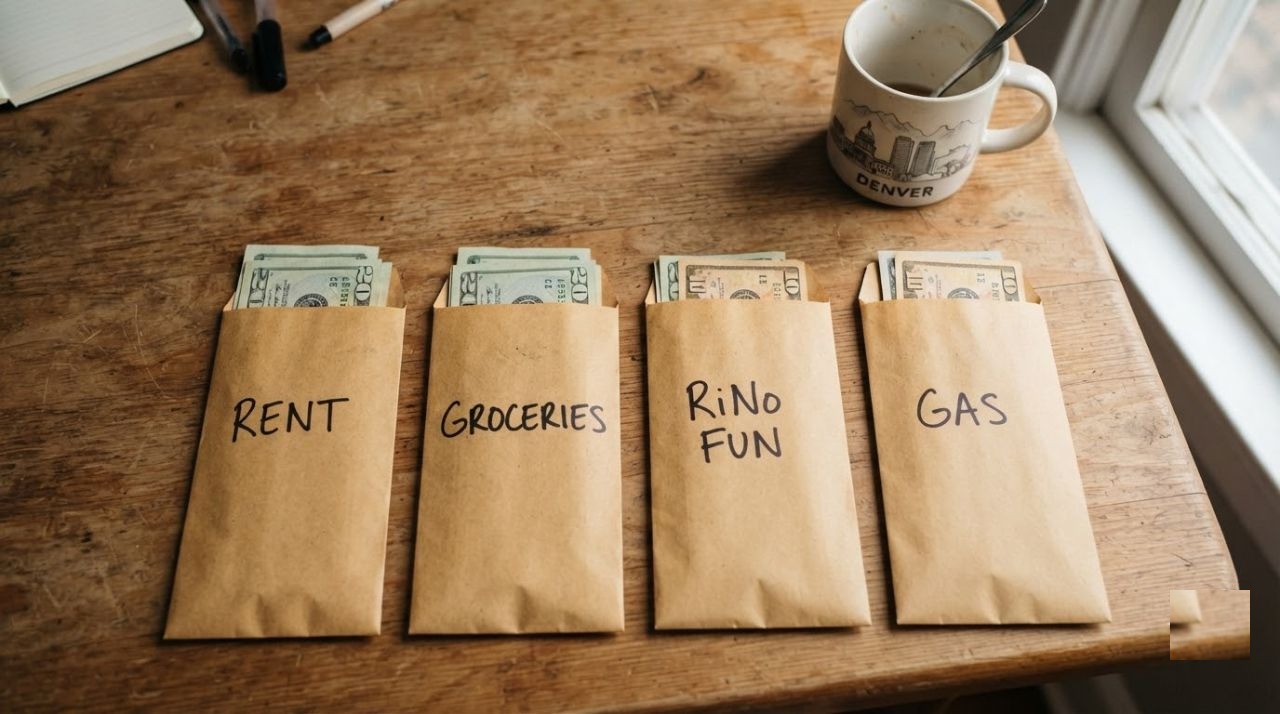
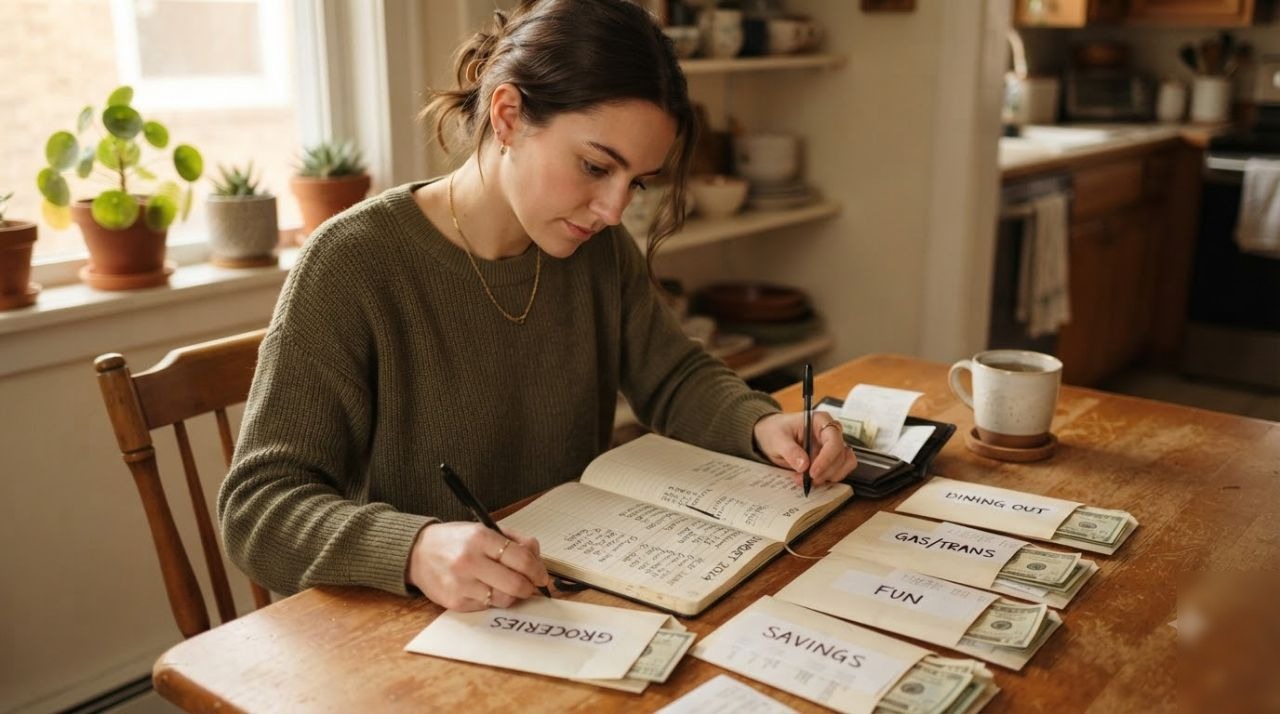
Cash stuffing is simple: withdraw your paycheck, divide it into labeled envelopes — rent, groceries, gas, “fun money” — and when an envelope’s empty, that category is closed for the pay period. No card, no “I’ll just tap it this once.”
The mechanics aren’t new. What’s changed is the environment fighting against it.
Denver is a city where “just one more thing” spending is baked into the lifestyle itself. A brewery patio after a hike, a ski-day lift ticket that turns into an après-ski tab, a RiNo gallery night that ends at a rooftop bar — none of it feels like “going out” because it’s framed as just living here. Your brain doesn’t flag a $70 lift-ticket-plus-lunch day as a splurge when everyone around you treats it as a normal Saturday.
That’s the exact gap cash stuffing closes. When your “going out” envelope has $55 left for the week, the decision gets made before you’re ordering a second round on a brewery patio.

Setting Up Your Envelopes for Denver’s Cost of Living
Generic budgeting advice splits spending into “needs and wants.” That breaks down here, because a lot of Denver’s “needs” got more expensive fast — driven by a wave of high earners who moved for lifestyle, not local wages catching up.
Start with what’s non-negotiable, sized to what things actually cost in this city:
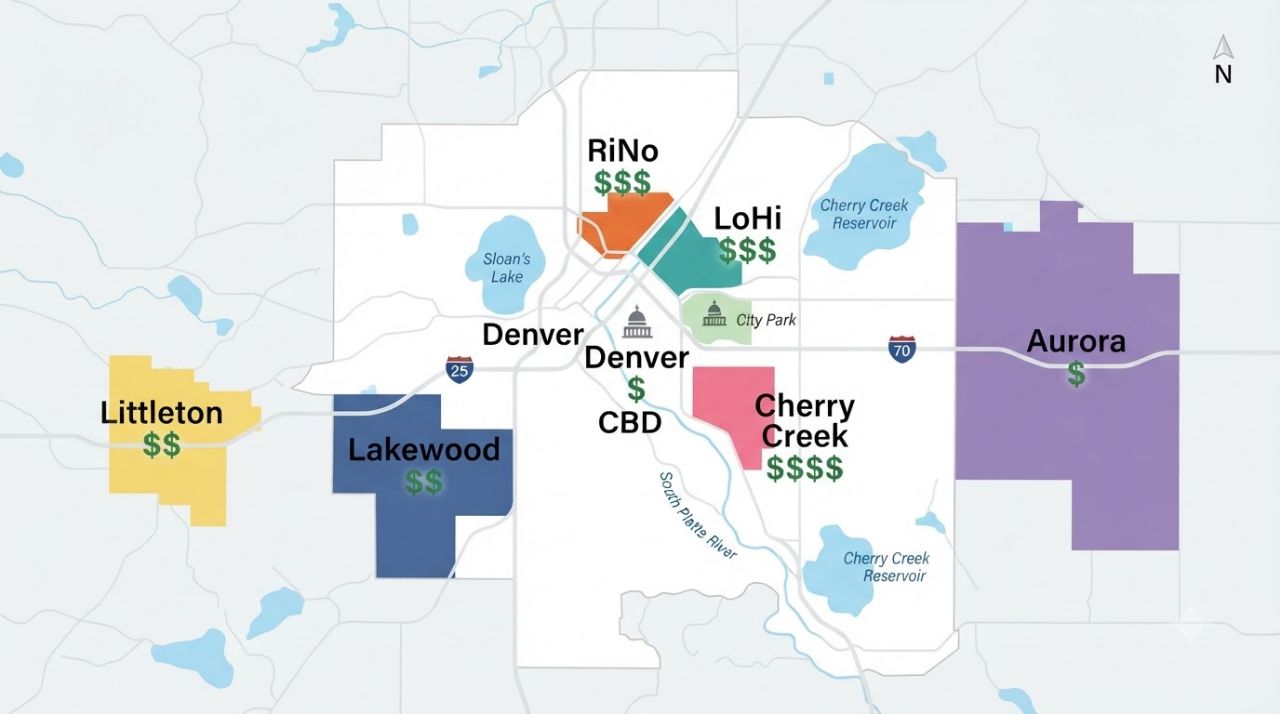
- Rent/mortgage envelope — not cash itself, but the anchor number everything else is built around. RiNo, LoHi, and Cherry Creek pricing looks nothing like Aurora or Lakewood pricing.
- Groceries — a Whole Foods run in Cherry Creek costs noticeably more than the same cart at a King Soopers or Sprouts out in Aurora or Littleton.
- Gas/transit — if you’re commuting from Broomfield, Littleton, or further out for a downtown job, this envelope needs to be honest about the real drive. RTD’s light rail helps if your route runs a line, but most of the metro still means driving.
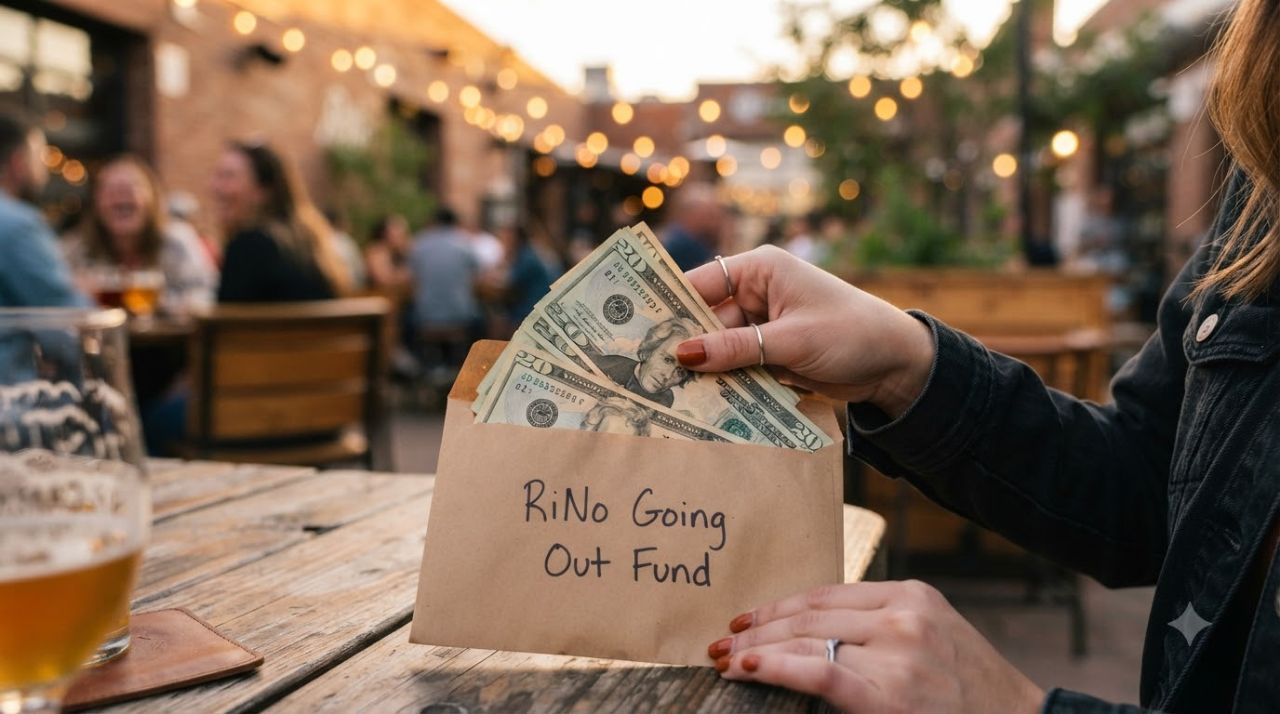
- “RiNo/going out” envelope — name it honestly. A vague “entertainment” category gets raided; a specifically-named one makes you pause before the third brewery stop.
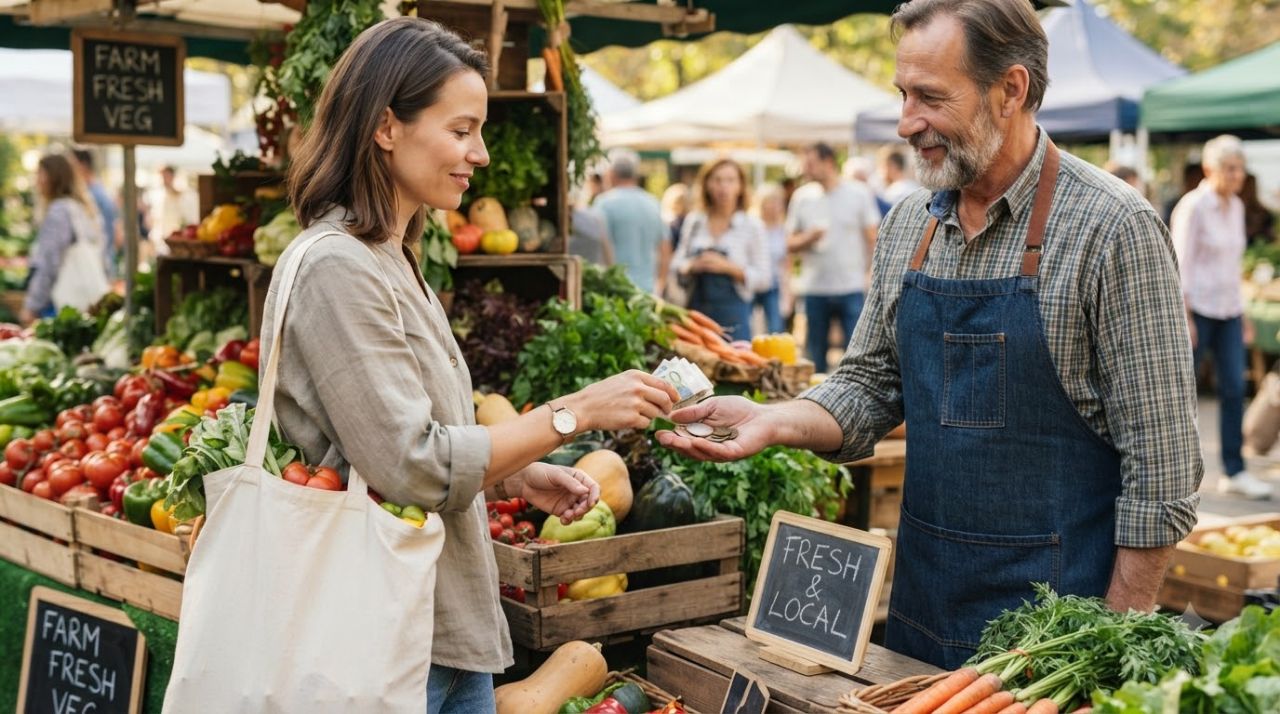
- Farmers market/local shopping — cash is often preferred at markets like the Cherry Creek Fresh Market and the South Pearl Street Farmers Market, so this envelope does double duty.
The Denver-specific move is naming your envelopes after your actual weak spots, not generic categories. If your money quietly disappears on brewery flights or ski-weekend extras, that envelope needs its own line — not a folder buried inside “entertainment.”
Where to Actually Get and Use Cash in Denver
This trips people up more than the budgeting math does — especially since Denver has one cash quirk most cities don’t.
A few Colorado-based options worth knowing:
- FirstBank — headquartered in Lakewood, Colorado, with a dense branch presence across the metro; a solid option if you’d rather your bank be a Colorado business.
- Canvas Credit Union (formerly Public Service Credit Union) — Colorado-based, often with better fee structures than national banks for regular withdrawals.
- Bellco Credit Union — headquartered in Greenwood Village, with wide ATM coverage across the Denver metro.
Pull your cash once at the start of the pay period, not in small withdrawals throughout the week — every extra ATM trip is another chance to overspend “just this once.”
There’s also a genuinely local reason cash matters more here than in most cities: Colorado’s legal cannabis industry still runs largely cash-only, because federal banking restrictions keep most dispensaries from accepting cards smoothly. If that’s part of your spending at all, it’s already forcing you to think in cash terms for that category — which makes it a natural fit to fold into an envelope instead of pulling extra ATM cash on the spot each time.
On the spending side, cash still gets you real value at the Cherry Creek Fresh Market, the South Pearl Street Farmers Market, food trucks around Civic Center Park and the Denver Central Market, and plenty of family-owned restaurants along Federal Boulevard’s international corridor.
Do Denver Neighborhoods Change How You Should Cash Stuff?
Yes — and this is the part most generic budgeting advice skips entirely.
If you live in RiNo or LoHi, your “food” and “going out” envelopes need to be bigger by default, because the breweries and restaurants in walking distance simply cost more. That’s not a discipline problem, it’s a zip code problem.
A friend of mine who moved from Aurora to LoHi for a shorter commute told me her eating-out envelope went from lasting three weeks to barely lasting ten days — same habits, same order at the same kind of restaurant, just a different neighborhood’s price tag attached to it. She didn’t get less disciplined. Her costs changed underneath her.
If you’re further out — Aurora, Lakewood, Littleton, or Broomfield — your gas/transit envelope needs to be honest about commute costs into downtown, but your food and entertainment envelopes can usually run smaller since there’s less built-in temptation within walking distance.
The mistake is copying a one-size-fits-all envelope split you found online instead of building one around your actual Denver zip code.
A Weekly Cash Stuffing Routine That Works With Denver Paydays
Here’s a simple routine to actually run this, week to week:
- Withdraw on payday, not the weekend before you need it. Downtown and RiNo ATMs get hit hard on weekends — some run low or trigger extra fees during Rockies home games, big RiNo Art District events, or the start of ski season.
- Sort into envelopes immediately, before the cash sits loose in your wallet. Loose cash gets spent without a category attached to it.
- Keep the “RiNo/fun” envelope physically separate from your everyday wallet — leave it at home on weeknights so it’s not tempting you on a random Wednesday happy hour.
- Do a Sunday check-in. Fifteen minutes, count what’s left in each envelope, adjust next week’s split if one category is chronically running dry.
- Roll over what’s left in flexible envelopes (like the farmers market one) into a small cash buffer instead of spending it just because it’s there.
If your pay schedule is biweekly rather than weekly, don’t just double every envelope and call it done — split the “RiNo/fun” and grocery envelopes into two smaller sub-piles for week one and week two instead. Otherwise it’s easy to blow through half a month’s fun money on one big ski weekend and coast on nothing until the next check lands. A rubber band and a sticky note with the week number on it is all the “system” you need.
The habit that actually moves the needle is step 3 — physically separating your temptation envelope from your daily-use cash. Everything else is math; that one is behavior.
Mistakes Denver Cash Stuffers Make
Underestimating ski-season spending spikes. Lift tickets, gear rentals, and the après-ski tab add up fast between November and March. Build a separate seasonal buffer instead of letting it wreck your regular envelopes.
Forgetting event weekends. Rockies games, RiNo art walks, and big downtown festivals spike crowds and prices across the city core. Plan around them instead of getting surprised by them.
Carrying too much cash at once on a brewery crawl. Cash stuffing doesn’t mean carrying your whole week’s envelope out for one night. Split what you’re carrying out from what stays safely at home.
Ignoring the credit union option. A lot of people default to a big national bank out of habit and eat ATM fees on every withdrawal — fees that quietly undo the savings cash stuffing is supposed to create.
If you’re brand new to the method, start with our cash stuffing for beginners guide to get the basic system down before layering on Denver-specific adjustments. And if you’re comparing notes with another city, see how the same method plays out in our cash stuffing Nashville guide and our cash stuffing Charlotte guide.
Final Thoughts
Denver’s growth has been great for the skyline and rough on a lot of paychecks that didn’t move here from a tech-salary city. Cash stuffing isn’t going to slow down how fast RiNo turns into another expensive neighborhood — but it does something you can actually control: it puts a visible, physical limit on the spending that happens because this city makes overspending feel like part of the lifestyle.
Start small. Pick your two or three biggest weak-spot categories — for most people here, that’s food and brewery/ski-adjacent spending — and stuff just those envelopes for one pay period. You’ll feel the difference before the month is out.
If Denver’s cost of living has been quietly draining your account, this is the cheapest fix you haven’t tried yet.
Frequently Asked Questions
Q: Is cash stuffing actually worth it in a lifestyle-heavy city like Denver where spending feels like part of living here?
A: Yes, arguably more so — the visible limit of an envelope counters exactly the kind of “this is just normal life here” spending pressure a place like Denver creates. It won’t lower your rent, but it stops the smaller leaks that add up fast around breweries, ski days, and patio season.
Q: Where can I withdraw cash without paying extra ATM fees in Denver?
A: Colorado-based options like FirstBank, Canvas Credit Union, and Bellco Credit Union have wide branch and ATM networks across the metro, which usually means more free, in-network machines than sticking with an out-of-state bank you brought with you.
Q: How much should I put in my “going out” envelope if I spend a lot of time in RiNo or LoHi?
A: Track one typical week honestly first — most people underestimate it by half. Set the envelope at that real number, then trim it 10–15% each pay period until it matches what you’re actually comfortable spending.
Q: Does cash stuffing still make sense if I moved to Denver from a much cheaper city?
A: It’s especially useful in that situation, since your spending instincts are calibrated to your old city’s prices, not Denver’s. Physical envelopes correct for that faster than a mental budget does, because the money running out is something you can see and feel, not just a number you have to remember to check.